Critical PHP2Shell Cyber Security Vulnerabilities – What UK Businesses Need
Home » Personal Insurance » Prestige & High Net Worth
If you are fortunate enough to have a high-value home you will find that many insurers and comparison sites are not able to offer the insurance solutions you need.
The definition of whether a home is Prestige and High Net Worth varies from Insurer to Insurer. It doesn’t have to a Stately Home or Country Manor, typically it may be a large home or even a smaller home where the cost of materials and labour involved in repairing or rebuilding the property and its contents will be ‘High Value’. In many cities the contents and valuables within penthouse apartments can easily fall into this category.
High net worth home insurance doesn’t have to be complicated. Our experienced team will get to know you, understand your lifestyle and assets, and arrange tailored protection at a competitive premium.
We can arrange policies tailored to your specific needs, including: –
Specialist advice for high net worth clients
We’re experienced high net worth home insurance brokers, not a call centre or comparison site.
We’ll work with you (and your advisers, if needed) to set realistic rebuild costs and contents sums insured, reducing the risk of underinsurance.
We understand complex situations – listed buildings, non-standard construction, multiple homes, collections, jewellery schedules and safe-requirements.
You’ll have named contacts who understand your cover and can act quickly when you need them.
If you ever need to claim, you won’t be left to deal with insurers alone. We’ll guide you through the process, liaise with loss adjusters and insurers on your behalf and help you achieve a fair outcome with minimal stress.
What is classed as a high net worth home? A high net worth home is typically a property whose rebuild value, contents or valuables are substantially above average — for example large country houses, listed / period homes, luxury apartments, or homes with significant contents, artwork or collections. These homes usually need bespoke cover because standard policies don’t reflect their true value or unique risks. If you are not certain we can also offer standard home insurance – see here.
Why is high net worth home insurance different from standard home insurance? Because high-value properties, contents and risks often exceed the limits and scope of standard home policies — high net worth insurance offers bespoke valuations, higher sums insured, broader coverage (valuables, worldwide cover, higher liability, etc.), and more personalised claims handling.
Can you cover jewellery, watches and artwork kept in a safe? Yes — we can provide cover for high-value jewellery, watches, artwork and other valuables whether in your home safe or securely stored elsewhere. Such items can be scheduled separately to ensure they are properly insured under a high-net-worth policy.
What if I have multiple homes or a holiday home? We can arrange cover for all properties under one policy or as separate policies — whether they are your main residence, a second home, holiday home or overseas property — ensuring each is appropriately insured for rebuild, contents and specific risks.
Can you work with my existing valuations or professional advisers? Absolutely — we routinely accept existing valuations (from surveyors, valuers or auction houses) and liaise with your professional advisers to ensure sums insured, valuations and policy terms reflect the true value and status of your home and contents.
Hot off the press - click to find out what is happening at Munro-Greenhalgh Ltd.
Critical PHP2Shell Cyber Security Vulnerabilities – What UK Businesses Need

We’ve done it again! Munro-Greenhalgh has been named Insurance Broker – The North at the UK Broker Awards 2026, adding a second prestigious national award to our centenary celebrations.

Most businesses understand the dangers of underinsurance and the application of Average. But providing insurers with inaccurate information could have even more serious consequences. Under the Insurance Act 2015, a breach of the Duty of Fair Presentation can result in claims being reduced, different policy terms being applied or, in the most serious cases, the policy being avoided altogether. And proportionate reductions aren’t necessarily limited to property claims — they could potentially have a significant impact on a multimillion-pound liability claim.

Munro Greenhalgh is proud to sponsor the Ramsbottom Raiders Under 8s home kit in 2026, supporting young players and grassroots football in our local community.
Critical PHP2Shell Cyber Security Vulnerabilities – What UK Businesses Need to Know Updated: 22 October 2026 An urgent cyber security warning has been
We’ve done it again! Munro-Greenhalgh has been named Insurance Broker – The North at the UK Broker Awards 2026, adding a second prestigious national award to our centenary celebrations.

Most businesses understand the dangers of underinsurance and the application of Average. But providing insurers with inaccurate information could have even more serious consequences. Under the Insurance Act 2015, a breach of the Duty of Fair Presentation can result in claims being reduced, different policy terms being applied or, in the most serious cases, the policy being avoided altogether. And proportionate reductions aren’t necessarily limited to property claims — they could potentially have a significant impact on a multimillion-pound liability claim.
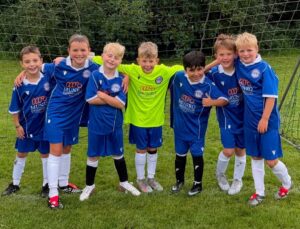
Munro Greenhalgh is proud to sponsor the Ramsbottom Raiders Under 8s home kit in 2026, supporting young players and grassroots football in our local community.